On Tells Investors It Will Nearly Double Sales by 2029. Wall Street Is Not Fully Buying It.
The Swiss running brand paired a CHF 5.6 billion sales target and a $1 billion buyback with growth numbers that keep slowing down.
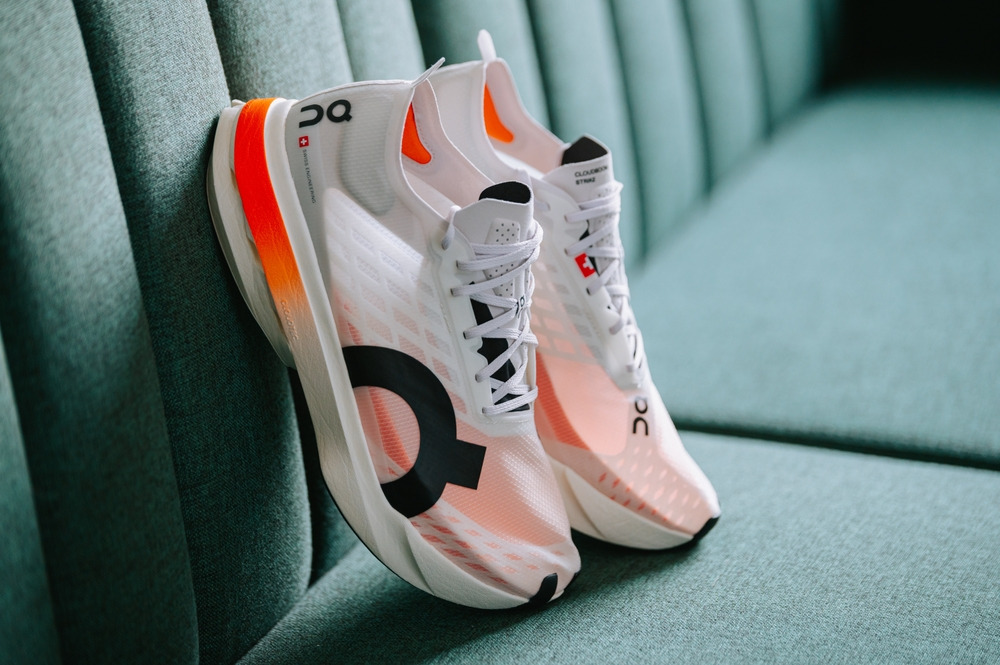
On used its September 22 investor day to make a bold claim: net sales nearly doubling to CHF 5.6 billion, roughly $6.8 billion, by 2029, on the back of high-teens annual growth, a gross margin held at 65% or higher, and adjusted EBITDA above 22%. The company also announced a $1 billion share buyback, the kind of move that says "we believe our own math" as loudly as any slide can.
The growth story leans on expansion well beyond running shoes, into apparel and new categories including soccer and golf, with the brand's newly signed Kylian Mbappé partnership positioned as the flag-plant for its move into football. It is the clearest sign yet that On intends to be a multi-sport lifestyle brand, not a running specialist that happens to sell well.
Analysts were, politely, skeptical. Jefferies noted growth has decelerated from 36% to 13% over six quarters and questioned whether On can close a 700-basis-point gap in its EBITDA margin target, while Needham modeled a more modest low-teens compound growth rate, crediting the brand for avoiding the deep discounting that has hollowed out margins elsewhere in athletic retail. A confident target is not the same thing as a guaranteed one, and On just spent a room full of analysts making sure everyone remembers the difference.
Kyle Duford, Founder & Editor, BRNDWIRE. More from Kyle →